
Galton Board and Trading; If the Next Trade is Random, Where is the Edge?
Galton Board and Trading; If the Next Trade is Random, Where is the Edge?
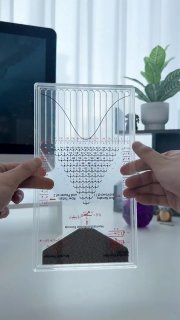
The Galton board experiment demonstrates an important principle about probability: the path of a single bead is unpredictable on its own, but when a large number of beads pass through the system, a distinct statistical pattern emerges in the collective behavior. Thus, the "unpredictability of an event" does not necessarily mean the "lack of structure in collective behavior." 🧐
📌 The fact that the next price movement is unpredictable does not prove that the market is completely random and that no Edge exists.
📊 A single order also does not provide complete information about the next price movement. The impact of a Buy Market depends on supply and demand, the amount of liquidity on the ask side, the price position, and orders that enter or cancel simultaneously. Therefore, one should not expect miracles from Order Flow or Volume; the importance lies in combining multiple events together.
💡 In market microstructure research, a meaningful relationship between Order Flow Imbalance (OFI) and price changes in short horizons has been studied, but its impact depends on market depth. For example, 100 units of buying in a market with 10,000 units of selling liquidity does not have the same effect as 100 units of buying in a market with only 500 units of selling liquidity. The ratio of order pressure to available liquidity also matters.
⚠️ However, statistical relationship does not mean absolute prediction. A positive OFI does not guarantee that the price will definitely go up; the market is a complex and dynamic system. Therefore, "statistical relationship ≠ absolute prediction" and "Edge ≠ certainty."
🔥Therefore, the Edge is not in the outcome of a single trade; it is in the distribution of outcomes across a large number of trades. Suppose a system, under specified conditions and after sufficient testing, has a 65% win rate and a 35% loss rate. This statistic does not mean the next trade is guaranteed to be a winner; even several consecutive trades can be losing ones. Edge means what distribution of outcomes you expect if you repeatedly execute conditions that possess an advantage.
🧠 This perspective is directly related to trading psychology. If we judge the system based on the outcome of every single trade, after a Stop Loss we might change the system or trade off-plan to recover losses. The problem is that we have confused the "trade outcome" with the "decision quality." The correct question to ask after a loss is: Was the trade executed exactly in accordance with the Edge and the system's rules?
📈 A bad decision can accidentally turn out profitable, and a correct decision can accidentally end in a loss. A single bead in the Galton board is uncertain; a single trade is no different. But across a large number of observations, the distribution of outcomes can be analyzed. The market is not a Galton board; this example does not prove that market returns are normal, and financial returns can have heavy tails.
🔍 A systematic outlook asks: "If I repeat these conditions many times, what will the distribution of outcomes be?" The result of a single trade cannot be controlled, but the entry rules, risk, trade execution, and the number of observations can be controlled.
✅ Ultimately, the issue is not predicting the next trade; we must understand whether our method truly creates an advantage in a suitable statistical sample and whether we can execute it consistently and without tampering across a large number of trades. If an Edge exists but its disciplined execution is not possible, we effectively have little advantage.
#Trading #Edge #Probability #OrderFlow
The Galton board experiment demonstrates an important principle about probability: the path of a single bead is unpredictable on its own, but when a large number of beads pass through the system, a distinct statistical pattern emerges in the collective behavior. Thus, the "unpredictability of an event" does not necessarily mean the "lack of structure in collective behavior." 🧐
📌 The fact that the next price movement is unpredictable does not prove that the market is completely random and that no Edge exists.
📊 A single order also does not provide complete information about the next price movement. The impact of a Buy Market depends on supply and demand, the amount of liquidity on the ask side, the price position, and orders that enter or cancel simultaneously. Therefore, one should not expect miracles from Order Flow or Volume; the importance lies in combining multiple events together.
💡 In market microstructure research, a meaningful relationship between Order Flow Imbalance (OFI) and price changes in short horizons has been studied, but its impact depends on market depth. For example, 100 units of buying in a market with 10,000 units of selling liquidity does not have the same effect as 100 units of buying in a market with only 500 units of selling liquidity. The ratio of order pressure to available liquidity also matters.
⚠️ However, statistical relationship does not mean absolute prediction. A positive OFI does not guarantee that the price will definitely go up; the market is a complex and dynamic system. Therefore, "statistical relationship ≠ absolute prediction" and "Edge ≠ certainty."
🔥Therefore, the Edge is not in the outcome of a single trade; it is in the distribution of outcomes across a large number of trades. Suppose a system, under specified conditions and after sufficient testing, has a 65% win rate and a 35% loss rate. This statistic does not mean the next trade is guaranteed to be a winner; even several consecutive trades can be losing ones. Edge means what distribution of outcomes you expect if you repeatedly execute conditions that possess an advantage.
🧠 This perspective is directly related to trading psychology. If we judge the system based on the outcome of every single trade, after a Stop Loss we might change the system or trade off-plan to recover losses. The problem is that we have confused the "trade outcome" with the "decision quality." The correct question to ask after a loss is: Was the trade executed exactly in accordance with the Edge and the system's rules?
📈 A bad decision can accidentally turn out profitable, and a correct decision can accidentally end in a loss. A single bead in the Galton board is uncertain; a single trade is no different. But across a large number of observations, the distribution of outcomes can be analyzed. The market is not a Galton board; this example does not prove that market returns are normal, and financial returns can have heavy tails.
🔍 A systematic outlook asks: "If I repeat these conditions many times, what will the distribution of outcomes be?" The result of a single trade cannot be controlled, but the entry rules, risk, trade execution, and the number of observations can be controlled.
✅ Ultimately, the issue is not predicting the next trade; we must understand whether our method truly creates an advantage in a suitable statistical sample and whether we can execute it consistently and without tampering across a large number of trades. If an Edge exists but its disciplined execution is not possible, we effectively have little advantage.
#Trading #Edge #Probability #OrderFlow
Persian original · View this post on Telegram ↗ · Open in the archive · 💬 Discuss in the Coin_Kurd Telegram group · Educational, not financial advice.